If you missed last week’s eye-opening webinar by Rob Harbin, the co-founder of Tactical Mind, AI, you can now watch it on recording by clicking on the following link:
https://tacticalmind.ai/lp/webinar-llms-vs-tacticalmindai
Monthly/Quarterly Portfolio Rebalancing vs. Triggered Re-Optimization
Did you notice that the first part of the title of this newsletter uses the term “rebalancing” and the second part uses “re-optimization”?
As we’ve been building our Tactical Mind AI tool (the industry’s first AI tool that will make specific portfolio recommendation changes, as well as let users create new portfolios from scratch that the tool can run), we’ve been beta-testing the concept of triggered re-optimization.
If you haven’t checked out Tactical Mind AI, you can at https://tacticalmind.ai.
What is “Classic” Monthly/Quarterly Portfolio Rebalancing?
If you work with 3rd party managers, you’ve heard them say, “this is a rebalance month.”
At the end of the month/quarter, managers evaluate their strategies based on their rules, signals, market conditions, etc., and decide what changes to make in portfolios (swapping out holdings and changing the percentages of current holdings).
Is the 1st day of the month arbitrary? Yep, but when you actively manage a strategy, you have to trade it periodically, and most firms use monthly or quarterly rebalancing.
When the strategy goes down 2%, 3%, 4%, or more a week before the end of the month/quarter, clients and advisors get pretty upset. Then they ask the manager, why didn’t you rebalance earlier? The typical response is simply that that’s the way the strategy is run.
What is Triggered Re-Optimization?
It’s when you add a trigger that would require the strategy to be re-optimized anytime during the month/quarter. This is DIFFERENT than saying the strategy is “tactically” managed. A strategy could be both “tactical” and use triggered re-optimization.
There are many different triggers, but I’m going to discuss one that has been written about in several papers. That trigger monitors the drawdown difference between the strategy and its benchmark.
Three White Papers on Triggered Re-Optimization
I found three interesting papers on this subject. To read, click on the following:
https://advisorstamp.com/trigger-papers
Moderate-risk portfolio example (60/40 stock-to-bond to a moderate-risk portfolio)
Let’s say the trigger is set up so that if the strategy intra-month is down 2% or MORE than the 60/40 benchmark, it triggers a re-optimization.
That could happen in the 1st, 2nd, or 3rd week of a month. If the strategy is supposed to beat the benchmark with lower risk, and if the strategy is down significantly more than the benchmark, that’s a sign that something is wrong.
TMAI example—while we didn’t build Tactical Mind AI to run model portfolios, we’ve been running them since June. Our Moderate-risk portfolio uses a 60/40 stock-to-bond portfolio benchmark.
The 3-month gross CAGR of the Tactical Mind AI moderate-growth portfolio = 3.82%
The 3-month gross returns of a 60/40 stock-to-bond portfolio = 0.74%
So, we’ve been happy with the strategy so far.
However, in September, we noticed that the TMAI model was down quite a bit more than the benchmark (an odd amount). This triggered a re-optimization.
-Without re-optimization, the return for Sept. would have been -3.38% (gross return).
-With re-optimization, the return for September would have been -2.85% (gross return).
-The 60/40 benchmark was down -1.24% for September.
Here are the 2026 gross returns of the TMAI moderate growth and a 60/40 portfolio:
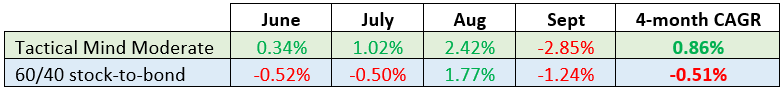
So what? The triggered re-optimization only saved 53 basis points for the month.
Well, let’s look at what the re-optimization for the TMAI Super Growth strategy in September:
-Without re-optimization = 4.28%
-With re-optimization = 6.22%
-Now the difference is 1.94% for the month.
FYI, the S&P 500 was down -0.33% for September.
The goal of triggered re-optimization isn’t to do knee-jerk re-optimization. We’d prefer it if re-optimization never happened.
But the question is: Does triggered re-optimization make sense?
What would a client say about rigid monthly/quarterly rebalancing vs. triggered re-optimization? I think they would say triggered re-optimization makes total sense. If things happen in the market where a rebalance is supposed to help, isn’t that what the consumer is paying the advisor for?
Why don’t firms use triggered re-optimization?
I think the answer is pretty simple; if a trigger goes off, most firms take days, if not weeks, to run a full rebalancing for their strategies. By the time they run the rebalance, the benefit could and most likely will be behind them.
Tactical Mind AI Can Run a Rebalance in Hours, NOT Days/Weeks
Tactical Mind AI to the rescue—Tactical Mind is like having 100 CFAs at your fingertips. Do you know how long it takes for the average strategy to run a rebalance? Only 3-4 hours!
Thought-provoking?
Hopefully, you found this newsletter to be thought provoking on two levels: 1) if you are managing money, should you set up re-optimization triggers? 2) Should you be using Tactical Mind AI to help make your portfolios better and help with the re-optimization process?
Tactical Mind AI is Soft-launching This Week
If you want a one-on-one demo of the tool to learn more about the industry’s most powerful portfolio manager/portfolio creating AI tool, click on the following link:
https://tacticalmind.ai/get-started.html
RoccyKnows YouTube Channel
Every week I’m posting a NEW YouTube video. Last week’s was on the Top 10 Roth Conversion Mistakes to Avoid. This week’s is on Estate Planning Mistakes to Avoid.
To watch the NEW consumer YouTube video, click on the following link or video:
https://www.youtube.com/@RoccyKnows/videos